Издатель
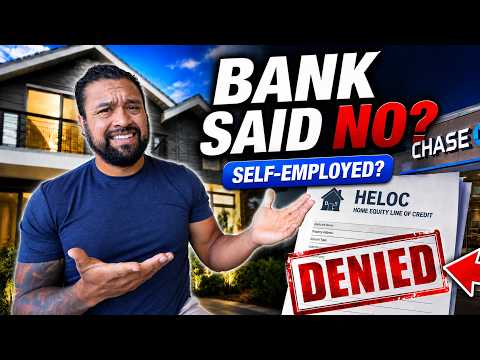
Are you self-employed and struggling to qualify for a traditional HELOC because your tax returns don’t show enough income?
In this video, I explain how a Bank Statement HELOC can help business owners and 1099 contractors access home equity using bank statements instead of tax returns.
Many self-employed borrowers have strong businesses, high deposits, and plenty of equity, but still get denied by banks because of write-offs on their tax returns. A bank statement home equity line of credit may be a better option because lenders can use 12 or 24 months of business or personal bank statements to calculate qualifying income.
In this video, I cover:
✅ What a Bank Statement HELOC is
✅ Who qualifies for a bank statement home equity line of credit
✅ How lenders calculate income using bank statements
✅ 50% expense factor vs lower expense factors
✅ Minimum credit score requirements
✅ How much equity you may be able to access
✅ HELOC draw periods and repayment terms
✅ Interest rates on bank statement HELOCs
✅ When a self-employed borrower should consider this option
✅ How to use home equity wisely for debt consolidation, business growth, or real estate investing
A Bank Statement HELOC is not for everyone, and interest rates can be higher than traditional HELOCs. But for self-employed homeowners who were denied by a bank, this type of loan can be a powerful way to access equity without relying only on tax returns.
If you are self-employed, have strong bank deposits, and want to see whether you qualify for a Bank Statement HELOC, reach out to Andes Mortgage today.
In this video, I explain how a Bank Statement HELOC can help business owners and 1099 contractors access home equity using bank statements instead of tax returns.
Many self-employed borrowers have strong businesses, high deposits, and plenty of equity, but still get denied by banks because of write-offs on their tax returns. A bank statement home equity line of credit may be a better option because lenders can use 12 or 24 months of business or personal bank statements to calculate qualifying income.
In this video, I cover:
✅ What a Bank Statement HELOC is
✅ Who qualifies for a bank statement home equity line of credit
✅ How lenders calculate income using bank statements
✅ 50% expense factor vs lower expense factors
✅ Minimum credit score requirements
✅ How much equity you may be able to access
✅ HELOC draw periods and repayment terms
✅ Interest rates on bank statement HELOCs
✅ When a self-employed borrower should consider this option
✅ How to use home equity wisely for debt consolidation, business growth, or real estate investing
A Bank Statement HELOC is not for everyone, and interest rates can be higher than traditional HELOCs. But for self-employed homeowners who were denied by a bank, this type of loan can be a powerful way to access equity without relying only on tax returns.
If you are self-employed, have strong bank deposits, and want to see whether you qualify for a Bank Statement HELOC, reach out to Andes Mortgage today.
- Категория
- Рефинансирование кредита
Комментариев нет.
Следующее
-
01:24

The HELOC Strategy the Wealthy Use to Pay Off Their Mortgage Faster #HELOC #VelocityBanking
-
00:55
How is a HELOC loan similar to a multi-tool? #loans #mortgagetips #DMV #heloc
-
01:24
Pay Off Your Mortgage in 3–12 Years? The HELOC Strategy Explained
-
00:59
Unlock the hidden wealth in your home: A guide to HELOC loans #heloc #mortgages #podcast
-
10:40
Learn From Others Mistakes: HELOC Case Studies |@TheClearCloseClips #heloc #homeequitylineofcredit
-
19:06
The Advanced HELOC Debt Consolidation Strategy Nobody Explains
-
09:38
How to Avoid Self Sabotage on Your Next HELOC | The Clear Close Clips #heloc #homeequitylineofcredit
-
08:30
Still Don't Get the HELOC Strategy? My Client Explains...
-
03:29
HELOC Loophole: How To GET $100k Online HELOC Loan Even With Tax Liens!
-
00:36
Why High Interest Rates Make the HELOC Strategy Even More Powerful
-
10:51

Обзор страхования на срок Unilife Life Insurance. Как работает срочное страхование жизни Юнилайф
-
1:17:48

Управление рисками.
-
18:21

Разбор 322 варианта Ларина, 19, 17 задание
-
06:27

Онлайн кредит. Онлайн заем. Коллектор әлегі.
-
23:35

Где взять кредит под ГАРАНТИРОВАННЫЕ 7,9% А под 0%? Рефинансирование кредита в ПОЧТА БАНК.
-
03:55
Можно ли получить рефинансирование ипотеки после реструктуризации?
-
03:13

Как взять кредит выгодно? Как узнать средние ставки по кредитам?
-
19:12

Лука призвал, в камере Тесака, удар по вкладам, 9 кг за 5 часов, дочь Сердюкова, Леон
-
04:30

✔ МТС Банк угрожает | Чушь несусветная 7 с
-
01:59

БЫСТРЫЙ КРЕДИТ НАЛИЧНЫМИ ЗА 5 МИНУТ. ОФОРМИТЬ ПОТРЕБИТЕЛЬСКИЙ КРЕДИТ ОНЛАЙН В ТИНЬКОФФ БАНКЕ.